
OBI Pharma just signed a deal worth more than US$2 billion without selling a single drug. On November 13, the Taiwanese company licensed its ADC platform technology to Novartis for a US$30 million signing fee and over US$2 billion in total potential value. [19][20]
Novartis is buying a method: how to attach a drug payload to an antibody with precision. OBI-902 and OBI's other in-house candidates are not listed as licensed assets in the announcement. [20]
How big and how certain is the money? The US$30 million is agreed at signing. The other 98%-plus depends on research, regulatory and sales milestones.
01 | Separate the upfront commitment from contingent value
The 17:17:30 MOPS announcement says the board approved the collaboration and authorized the chairman to arrange signing.
OBI’s Chinese and English releases describe an agreement already entered into.
Neither publishes signature pages or a separate effective date; these distinct statements should retain their original scope.[16][19][20]
The $30 million is a contractual upfront commitment.
Payment timing, refundability and actual receipt have not been disclosed.
The headline exceeding $2 billion is total potential deal value, including conditional milestones, rather than milestones to which another $30 million should automatically be added.[19][20]
| Agreed upfront commitment | Conditional future proceeds |
|---|---|
| $30m; timing, refundability and receipt status undisclosed | Development, regulatory and commercial milestones; category caps undisclosed; total potential deal value exceeds $2bn |
| Contractually agreed; public receipt confirmation unavailable | Tiered royalties on licensed-product net sales; rates and thresholds undisclosed |
Dividing $30 million by a total exceeding $2 billion gives an upfront share below 1.5%.
This is an upper bound, not an exact percentage: the announcement provides only a lower bound for total value.
The English release confirms tiered royalties, while the Chinese version describes a net-sales share without specifying tiers.[20]
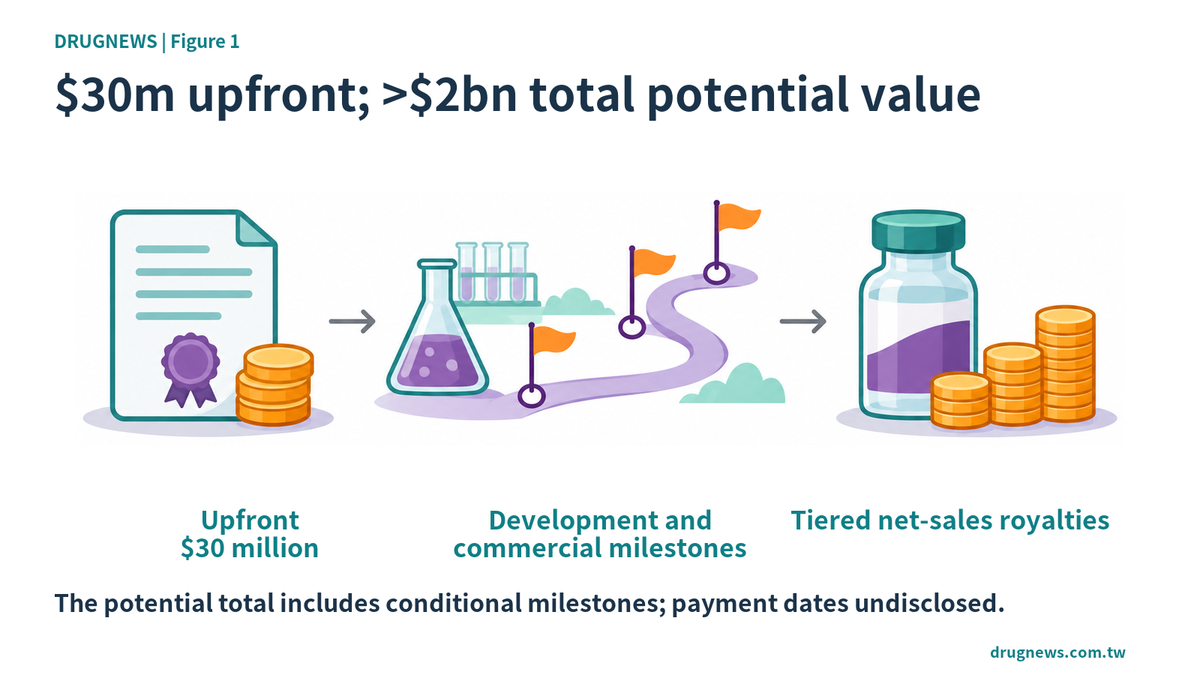
The $30 million is an agreed upfront; the headline value includes payments requiring future achievements.
02|Why Novartis moved now
Novartis has been placing ADC bets all year. In July it agreed to buy Myricx for up to US$1.5 billion, acquiring a novel payload class. [22]
The payload is the warhead of an ADC. Having a warhead is not enough: it has to sit on the antibody at a fixed site, at a consistent dose, and stay attached in the bloodstream. That is what OBI's four platforms do. [20]
The announcement defines the exclusive scope by "specific Novartis payload classes" and does not name them. The direction is clear all the same: the more payloads Novartis owns, the more it needs conjugation technology.
OBI now holds a place in a big-pharma ADC research chain. Milestones and royalties arrive only as the partnered products advance.
03 | The disclosed exclusive field is defined by payload classes
An ADC combines an antibody with a drug payload through a linker.
Which target the antibody recognizes and which payload class it carries are separate ways to define a license.
OBI’s release explicitly uses selected, undisclosed Novartis payload classes to describe exclusivity.[20]
The named technologies are GlycOBI, EndoSymeOBI, HYPrOBI and GlycOBI DUO, covering glycan-based conjugation, enzymatic processing, hydrophilic linkers and dual-payload designs.
Novartis receives worldwide exclusive rights to related patents and know-how within the agreed field.
| Term | What is disclosed (brief original wording or paraphrase) | Practical meaning (interpretation) |
|---|---|---|
| Asset and exclusive field | “selected, undisclosed Novartis payload classes”; related patents and know-how.[20] | Payload boundary disclosed; additional target limits, target count and indications undisclosed; no whole-platform acquisition. |
| Development milestones | Development progress is a payment category.[19][20] | Triggers and category cap undisclosed. |
| Regulatory milestones | Regulatory progress is a payment category.[19][20] | Jurisdictions, approval events and category cap undisclosed. |
| Commercial milestones and royalties | Commercial progress; “tiered royalties on net sales”.[20] | Commercial cap, sales thresholds, royalty rates and term undisclosed. |
| Research work and funding | OBI evaluates novel linker approaches with Novartis payloads.[20] | Other conjugation work, clinical/commercial duties and cost allocation undisclosed; separate service fees versus upfront funding undisclosed. |
| Expansion option | Additional novel payload classes may be included.[20] | Exercise price, expiry, class count and whether expansion payments are in headline value undisclosed. |
| OBI’s retained rights | No transfer of OBI-902 or OBI-904 is identified; full reservations unpublished.[19][20] | Restrictions on internal programs, other licensing and non-compete obligations undisclosed; unrestricted freedom cannot be assumed. |
| Duration, termination and reversion | Duration, termination and change-of-control provisions undisclosed.[19][20] | No public basis to determine rights reversion or treatment of amounts paid. |
This summarizes public disclosures, not the complete contract.
The November 13 MOPS filing uses a general material-event format rather than six dedicated contract fields.
Missing terms cannot be filled with provisions from OBI’s separate November 11 Taiwan collaboration.[19]
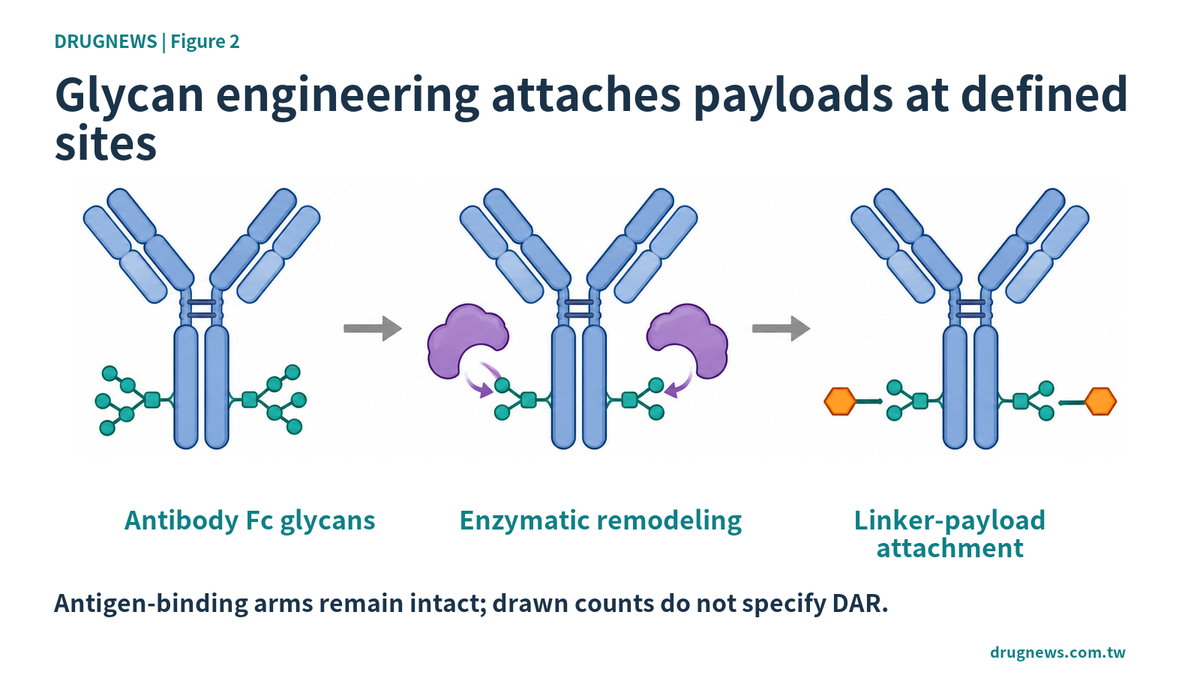
The platform controls conjugation; each resulting product needs its own development evidence.
OBI’s specific disclosed task is evaluating linkers with Novartis payloads.
OBI’s website continues to list internal programs including OBI-902 and its existing territorial arrangements.
That is compatible with platform licensing.
04 | Compare fields, options and work before comparing price
These platform-enabled transactions divide rights differently: by payload class, nominated targets, a research-stage option or resulting collaboration ADCs.
The table therefore compares structure, including what the releases leave unanswered.[11][12][21]
| Platform / partner; date | Upfront / total potential consideration | Unit of scope | Option or expansion | Licensor’s retained rights and work |
|---|---|---|---|---|
| OBI / Novartis; 2026-11-13 | $30m / >$2bn; <1.5% | Selected undisclosed Novartis payload classes; target limits undisclosed | Additional payload classes; price and expiry undisclosed | OBI evaluates linkers; reservations for internal/other programs and subsequent cost allocation undisclosed.[20] |
| Synaffix / Boehringer; 2025-01-09 | Upfront undisclosed; up to $1.3bn additional milestones; ratio unavailable | Agreed, undisclosed number of targets | First target at signing; others within a predefined period; no separate paid option identified | Target-specific technology model; other contractual reservations and limits undisclosed.[21] |
| Araris / Chugai; 2026-02-10 | Immediate upfront on exercise, amount undisclosed; overall RCO up to about $780m; ratio unavailable | This exercise covers one Chugai-selected target | Research then option exercise; overall value requires all options and milestones | AraLinQ platform license; other-target, internal-program and relicensing reservations undisclosed.[11] |
| DualityBio / Genentech; 2026-08-28 | $45m / ($45m + >$1bn milestones); <4.31% | Exclusive worldwide collaboration ADCs against Genentech-defined targets | Expansion option undisclosed | DualityBio leads discovery through Phase 1a; Genentech takes later clinical development and commercialization; other reservations undisclosed.[12] |
Ratios exclude royalties, which have no disclosed aggregate value.
Araris’s approximately $780 million covers the overall RCO, conditional on all options and milestones; it is not the value of the single target licensed in February.
Synaffix’s $1.3 billion is additional milestones, not total consideration.[11][21]
OBI’s $30 million is below the other disclosed upfront here, DualityBio’s $45 million.
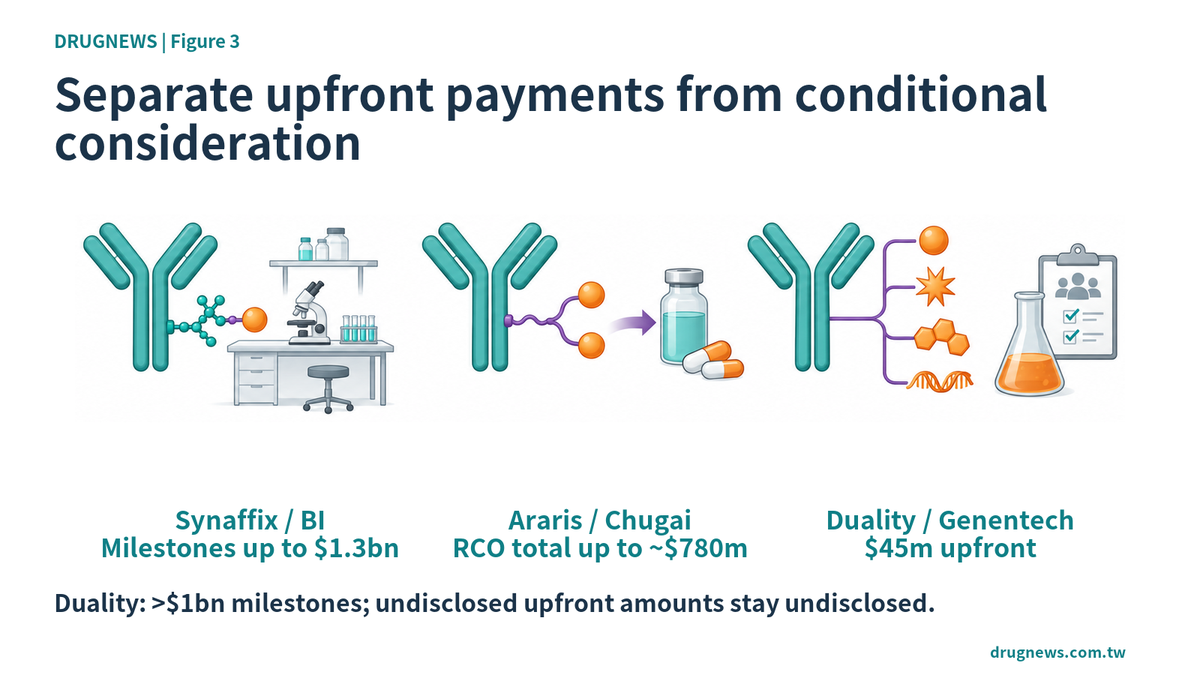
Compare licensed scope and research obligations before headline amounts.
05 | What the upfront means for a Taiwan platform business
At the central bank’s November 13 closing rate of NT$32.838 per US dollar, the upfront converts to about NT$985 million.
This is a comparison convention, separate from OBI’s actual currency conversion, tax and receipt timing.[17]
R&D expense was NT$1.729 billion in 2025 and NT$1.968 billion in 2024.[2]
OBI reported NT$643 million in R&D expense and NT$858 million in operating cash outflow for the first nine months of 2026.
Dividing the converted upfront by average monthly operating cash outflow gives about 10.3 months of historical spending; the 2025 cash-outflow baseline of NT$2.020 billion gives 5.9 months.[2][18]
These are spending equivalents, not a runway forecast or proof of cash received.
They exclude unearned milestones.
September cash and equivalents were NT$330 million, with a separate NT$140 million of current financial assets at amortized cost; the latter should remain a separate balance-sheet category.[18]
In 2025, OBI stopped the OBI-822/OBI-821 Phase III study and redirected resources toward ADCs.
The Novartis collaboration now puts its platform into an international partner’s payload development work.[13][20]
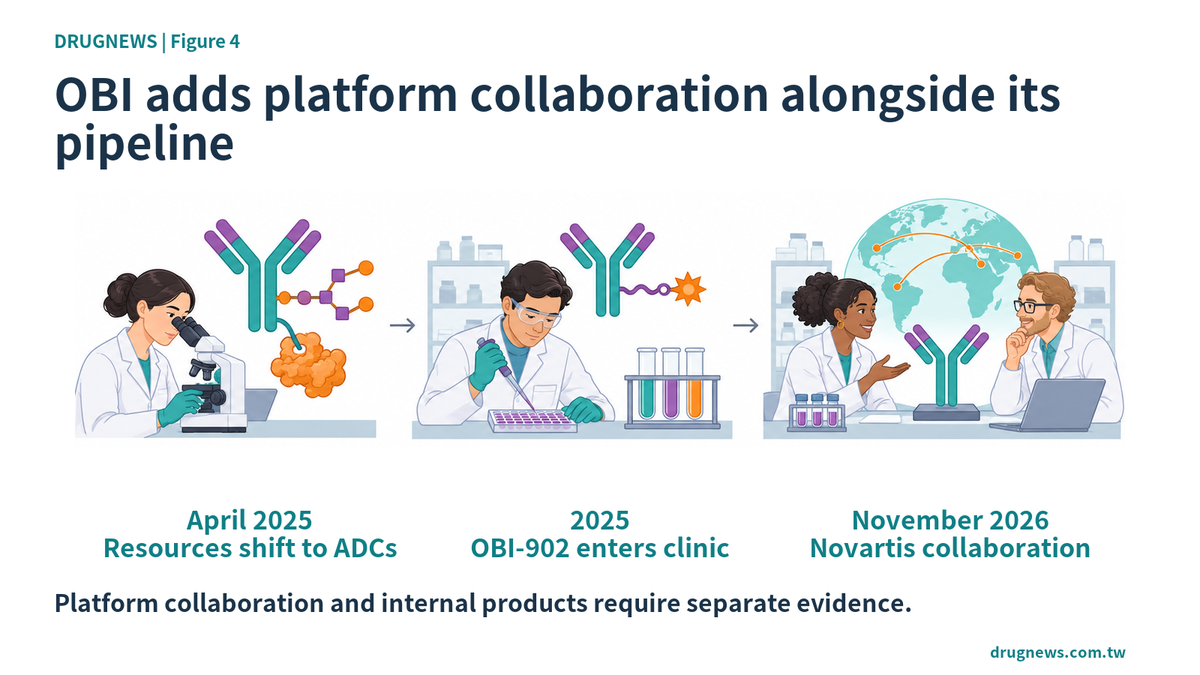
OBI’s website still lists internal programs; the full contractual reservations remain unpublished.
06 | Five things the contract has not disclosed
- Beyond payload class, does exclusivity also restrict targets, target count or indications, and how does it affect OBI-902, OBI-904 and other partnerships?
- When is the $30 million payable, is it refundable, and can category milestone caps and royalty tiers be disclosed?
- Is OBI’s linker research separately funded, and who performs and pays for other conjugation work, clinical development and commercialization?
- When does the payload-expansion option expire, what does exercise cost, and are expansion payments already in the headline value?
- What are the contract duration and termination or change-of-control arrangements for results, licensed rights and amounts paid?
07|Watch the first milestone
US$2 billion is the ceiling and US$30 million is the starting point. The partnered products have to cover the distance between them.
Two signals matter. First, a research milestone: whether OBI's linkers paired with Novartis payloads yield a clinical candidate. Second, whether Novartis exercises its option to add payload classes. Either one would reset the value of this contract.
For Taiwan biotech this is a new template: a technology platform can be licensed to a global pharma on its own, with the in-house candidates left out of the deal.
References
- [2] 2025年合併財務報告,頁8、10、13|OBI Pharma|2026-03-09|https://www.obipharma.com/investor-overview/financial-report/
- [5] Technology Platform|OBI Pharma|2026-11-13查閱,頁面未標發布日|https://www.obipharma.com/what-we-do/technology-platform/
- [6] Pipeline Overview|OBI Pharma|2026-11-13查閱,頁面未標發布日|https://www.obipharma.com/what-we-do/pipeline-overview/
- [11] Chugai and Araris enter license agreement|Chugai|2026-02-10|https://www.chugai-pharm.co.jp/english/news/detail/20260210173000_1227.html
- [12] Global collaboration with Genentech on DUPAC|DualityBio|2026-08-28|https://en.dualitybiologics.com/news/614.html
- [13] OBI decided to terminate OBI-822 Phase 3 study|OBI Pharma|2025-04-23|https://www.obipharma.com/announcement/obi-decided-to-terminate-obi-822-phase-3-study-based-on-dsmbs-recommendation-and-to-redirect-resources-towards-adcs-development/
- [16] 台灣浩鼎與諾華簽署合作暨授權協議,瀏覽器完整正文|台灣浩鼎|2026-11-13|https://www.obipharma.com/zh-hant/news/signs-collaboration-and-license-agreement-with-novartis/
- [17] 新臺幣/美元銀行間收盤匯率32.838|中央銀行|2026-11-13|https://www.cbc.gov.tw/tw/mp-1.html
- [18] 115年第3季合併資產負債表、綜合損益表及現金流量表|MOPS/4174|2026-11-13查閱,報表期末2026-09-30|https://mopsov.twse.com.tw/mops/web/t164sb03
- [19] 公告本公司召開重大訊息記者會新聞稿內容,序號3、17:17:30|MOPS/4174|2026-11-13|https://mopsov.twse.com.tw/mops/web/ajax_t05st01?firstin=true&step=2&off=1&TYPEK=otc&co_id=4174&spoke_date=20261113&spoke_time=171730&seq_no=3
- [20] Collaboration and License Agreement with Novartis,英文完整正文|OBI Pharma|2026-11-13|https://www.obipharma.com/news/signs-collaboration-and-license-agreement-with-novartis/
- [21] Boehringer Ingelheim broadens oncology portfolio,Synaffix公司原始發布稿|Synaffix B.V./PR Newswire|2025-01-09|https://www.prnewswire.com/news-releases/boehringer-ingelheim-broadens-oncology-portfolio-with-license-for-synaffixs-adc-technology-302346940.html
- [22] Novartis agrees to acquire Myricx Bio, advancing next-generation antibody-drug conjugate innovation with a novel NMTi payload, expanding options for cancer patients|Novartis|2026-07-06|https://www.novartis.com/news/media-releases/novartis-agrees-acquire-myricx-bio-advancing-next-generation-antibody-drug-conjugate-innovation-novel-nmti-payload-expanding-options-cancer-patients
This article provides industry and company analysis and does not constitute investment or medical advice.
Share this analysis
Send this article to readers who follow biotech, company strategy, and capital-market signals.
Cite this article
For decks, research notes, or media references, cite Drugnews with the canonical article URL.
Drugnews Editorial Team. "OBI's $2B Novartis Deal Sells the Platform, Not a Drug." Drugnews, Nov 15, 2026. https://drugnews.com.tw/articles/2026-11-15-obi-novartis-adc-platform-en.html